Fortifying Families, Commercial Properties, and Retail Operations Against Autumn Premises Liability and High-Traffic Risks
Halloween represents one of the most vibrant, community-centered traditions of the autumn calendar. Neighborhood streets fill with trick-or-treaters, private residences transform into elaborate walk-through displays, and commercial main streets host family-oriented festivals, pop-up events, and extended retail promotions.
The convergence of dark autumn evenings, heavy foot traffic, costumed visitors with restricted peripheral vision, open candle flames, and unvetted sidewalk hazards turns an evening of celebration into one of the most legally volatile nights of the year.
A single trip over an unlit extension cord, a burns incident from an open jack-o’-lantern flame, or a crowd-crush injury at an overcrowded commercial doorway can rapidly escalate into a high-dollar personal injury lawsuit.
At Skyscraper Insurance, we analyze personal and commercial risk through a proactive risk-engineering lens. Enjoying a safe, festive Halloween requires combining disciplined on-the-ground safety protocols with a forensic review of your personal and commercial liability coverage.
1. Top Liability Vectors on Halloween Night: Homes & Businesses
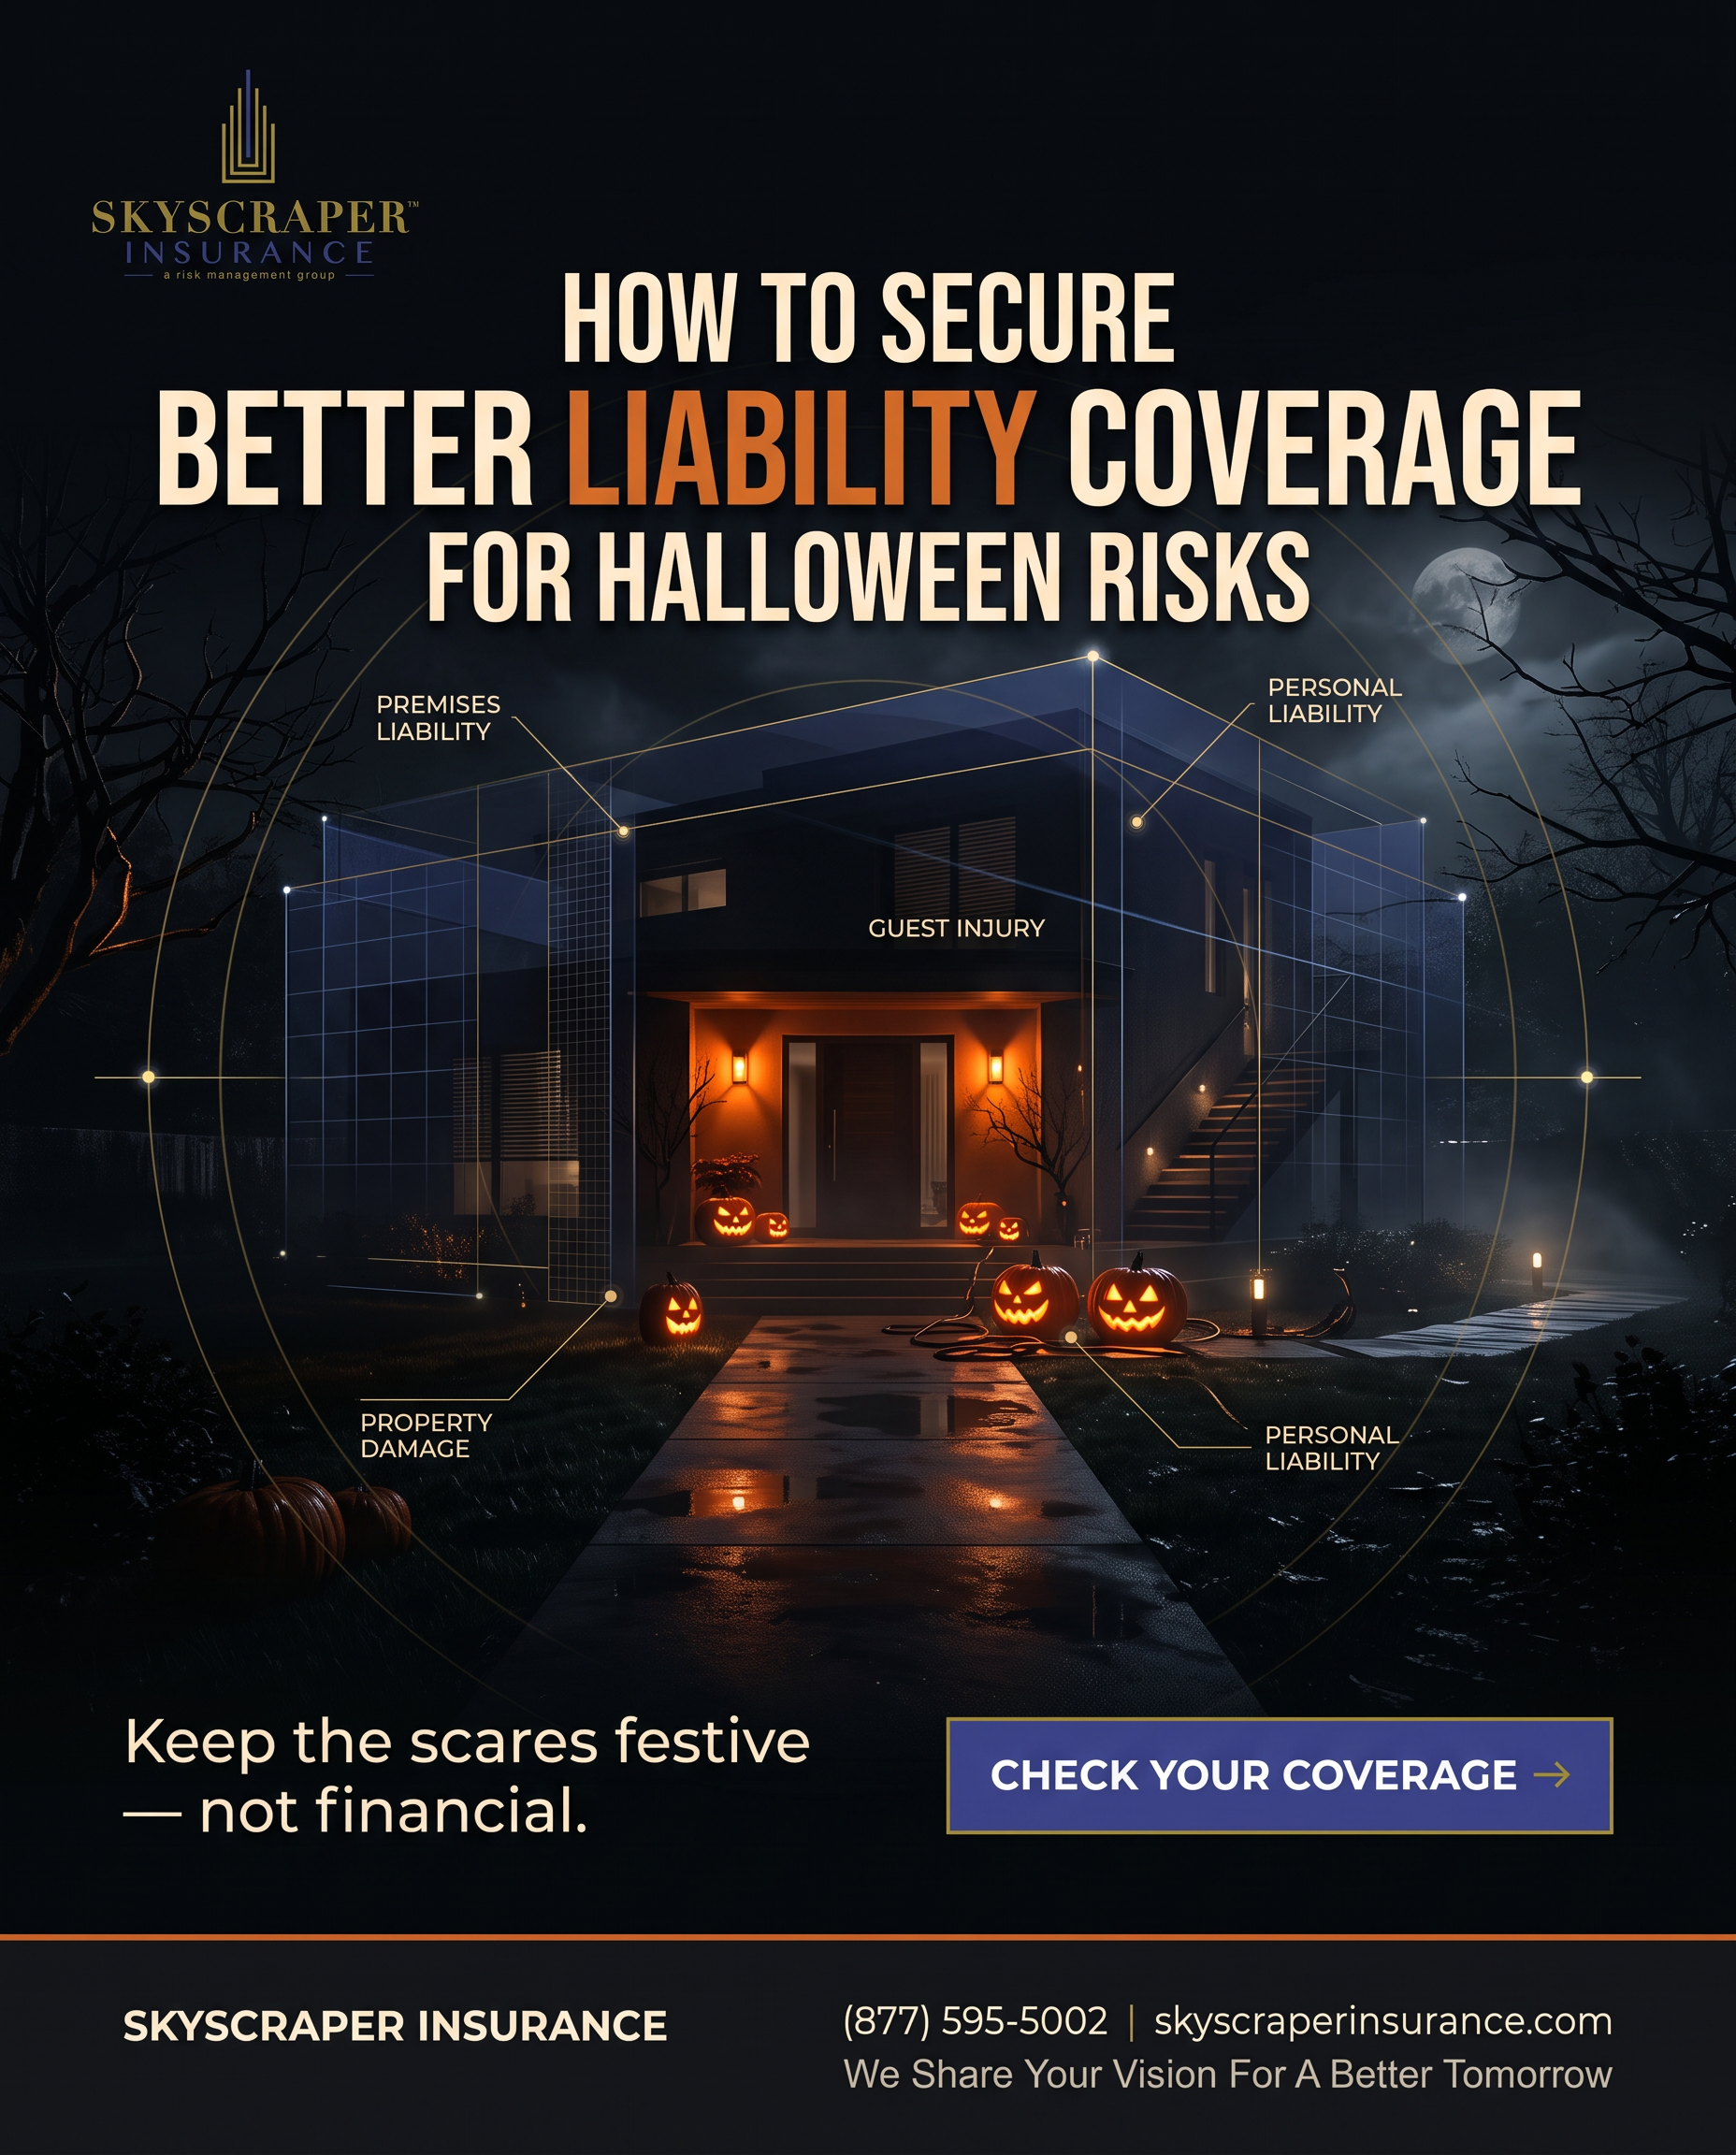
- Pedestrian Slips, Trips, and Falls: Low ambient lighting combined with masks, long hemlines, and excited children creates high-frequency trip hazards. Uneven walkway pavers, wet leaves, hidden garden hoses, temporary extension cords powering fog machines, and unlit porch steps are primary drivers of premises bodily injury claims.
- Fire Hazards from Open Flames & Decorative Lighting: Traditional candles placed inside carved pumpkins or decorative paper lanterns present immediate fire exposures. Long costumes brushing against an open flame on a narrow porch, or overloaded electrical outlets powering complex lighting displays, can spark rapid structure fires and catastrophic burn injuries.
- Canine and Domestic Pet Agitation: Constant doorbell ringing, unusual costumes, unfamiliar masks, and loud noises can disorient and agitate even the calmest family pets. Dog bite and knock-down incidents spike significantly on Halloween, generating severe premises liability claims that standard personal policies often sub-limit or exclude based on breed.
- Retail Overcrowding and Ingress/Egress Bottlenecks: For storefront businesses and venues participating in “trunk-or-treat” or community events, surges in foot traffic test physical entryways and emergency exits. Merchandising displays blocking aisles, unmoored exterior pop-up tents, and poorly managed queues create substantial commercial general liability friction.
The Social Inflation Warning
2. Practical Safety Checklist: Mitigating Risk on the Ground
Proactive physical prevention is always the primary line of defense.
Clear and Illuminate All Walkway Paths
Inspect all primary walkways, driveways, and entry stairs. Sweep away damp leaves, stow garden tools, and tape down or elevate all electrical wiring. Replace low-wattage accent bulbs with bright, high-lumen floodlights to ensure visitors can clearly see steps, elevation changes, and path boundaries.
Transition Entirely to Flameless LED Lighting
Eliminate all open flames. Replace conventional wax candles in jack-o’-lanterns and window displays with battery-powered LED tea lights or glow sticks. Inspect all outdoor UL-rated decorative lighting strings for frayed cords or damaged sockets, and avoid daisy-chaining multiple extension cords into a single non-GFCI outlet.
Secure Family Pets in a Quiet, Enclosed Area
Keep pets safely confined in an interior room away from front entryways and noise. This prevents unexpected escapes into busy street traffic and eliminates the risk of an anxious pet jumping on, scratching, or biting a startled visitor.
Establish Controlled Ingress/Egress for Commercial Spaces
Commercial venues and retail storefronts must maintain wide, unobstructed pathways into and out of the store. Keep exits illuminated and free of decorative cobwebs, signs, or temporary display racks. Assign staff members to monitor exterior queue lines and oversee spill-cleanup protocols immediately.
3. Coverage Forensics: Fortifying Your Policy Towers
Physical precautions significantly reduce incidents, but complete financial resilience requires verifying that your underlying insurance contracts respond without dispute if an injury occurs:
Personal Lines: The Underlying Umbrella Attachment
Standard homeowners policies (HO-3 / HO-5) typically carry baseline personal liability limits of $300,000 to $500,000. In a catastrophic injury case involving permanent disfigurement or neurological damage, these caps are instantly breached. Verifying that an overarching Personal Umbrella Tower ($1M to $5M+) is active—and confirming that underlying homeowners liability limits meet the exact attachment threshold required by your umbrella underwriter—is essential to protect personal equity.
Commercial Lines: Premises Medical Payments & Aggregate Caps
For commercial real estate managers and retailers, audit your Commercial General Liability (CGL) policy. Ensure your Medical Payments (“Med Pay”) sub-limit is appropriately sized ($5,000 to $10,000+).
Specialized Animal and Attractive Nuisance Carve-Ins
Audit your personal binder for restrictive animal liability exclusions or attractive nuisance limitations (especially if your Halloween display features walk-through haunted tunnels, elevated platforms, mechanical animatronics, or bounce houses). If high-risk decorative setups are present, specialized endorsements must be affirmatively added to avoid claim denials.
Standard Coverage Gaps vs. The Skyscraper Protection Standard
| Exposure Point | Generic Baseline Policy | The Skyscraper Insurance Standard | Balance Sheet Advantage |
| Walkway Trip & Fall | Standard $300k limit; defense costs may erode primary limits. | Seamless High-Limit Umbrella ( | Completely insulates personal investment accounts and real estate equity. |
| Pet Agitation & Bites | Restrictive breed lists, strict sub-limits, or total exclusions. | Audited Animal Liability Terms: Broad affirmative liability wording. | Eliminates out-of-pocket settlement exposures from pet-related incidents. |
| Commercial Event Foot Traffic | Single general aggregate shared across all retail operations. | Per-Location Aggregate & Enhanced Med Pay: Rapid incident de-escalation. | Settles minor medical bills quickly without triggering lengthy commercial lawsuits. |
| Temporary Props & Exhibits | Denials under “attractive nuisance” or business pursuits clauses. | Affirmative Event & Exhibit Endorsements: Explicitly cleared underwriting terms. | Protects creative displays and pop-up events against third-party liability disputes. |
Take Control: Check Coverage
Halloween should be an evening of celebration, neighborly connection, and seasonal entertainment, not the origin point of a devastating personal or corporate liability claim. Leaving your personal wealth or commercial balance sheet exposed to slip-and-fall claims, pet incidents, or decorative fires with an uninspected, generic insurance binder is an uncalculated gamble.
At Skyscraper Insurance, we specialize in comprehensive risk engineering, commercial property placement, and high-net-worth personal lines architectures. Our advisors perform forensic policy reviews, identify hidden premises exclusions, size umbrella towers to your true net worth, and place tailored coverage with premier global underwriters.
Are your home and business liability limits structured to absorb high-traffic seasonal risks, or will a single holiday incident expose your assets to modern litigation?
Fortify your property before the festivities begin. Connect with our dedicated advisory team today and Check Coverage. We will conduct a thorough, confidential audit of your active personal and commercial liability programs to ensure you, your family, and your business remain fully protected under every scenario.
Visit us at Skyscraper Insurance to schedule your liability review today.