October marks a distinct seasonal turning point. As temperatures begin to cool, leaves change, and households prepare for the upcoming holiday season, autumn brings noticeable shifts in everyday routines. Yet, amidst the busy start of the fourth quarter, this transitional month also introduces a sharp escalation in seasonal property hazards, from heavy autumn rainstorms and fluctuating temperatures to early freeze cycles and heightened home heating usage.
Your home is your most valuable personal asset and the sanctuary of your daily life.
Too many homeowners assume that an off-the-shelf home insurance binder automatically protects against any damage the season brings.
At Skyscraper Insurance, we treat personal property protection with the same analytical rigor, technical precision, and foresight as enterprise commercial lines. Kicking off October requires looking closely at your active homeowners coverage to ensure your dwelling, personal valuables, and household balance sheet are completely fortified for the months ahead.
1. Autumn Weather and Seasonal Risk Escalation
As autumn settles in, specific weather events and seasonal home habits create frequent, high-cost property claims:
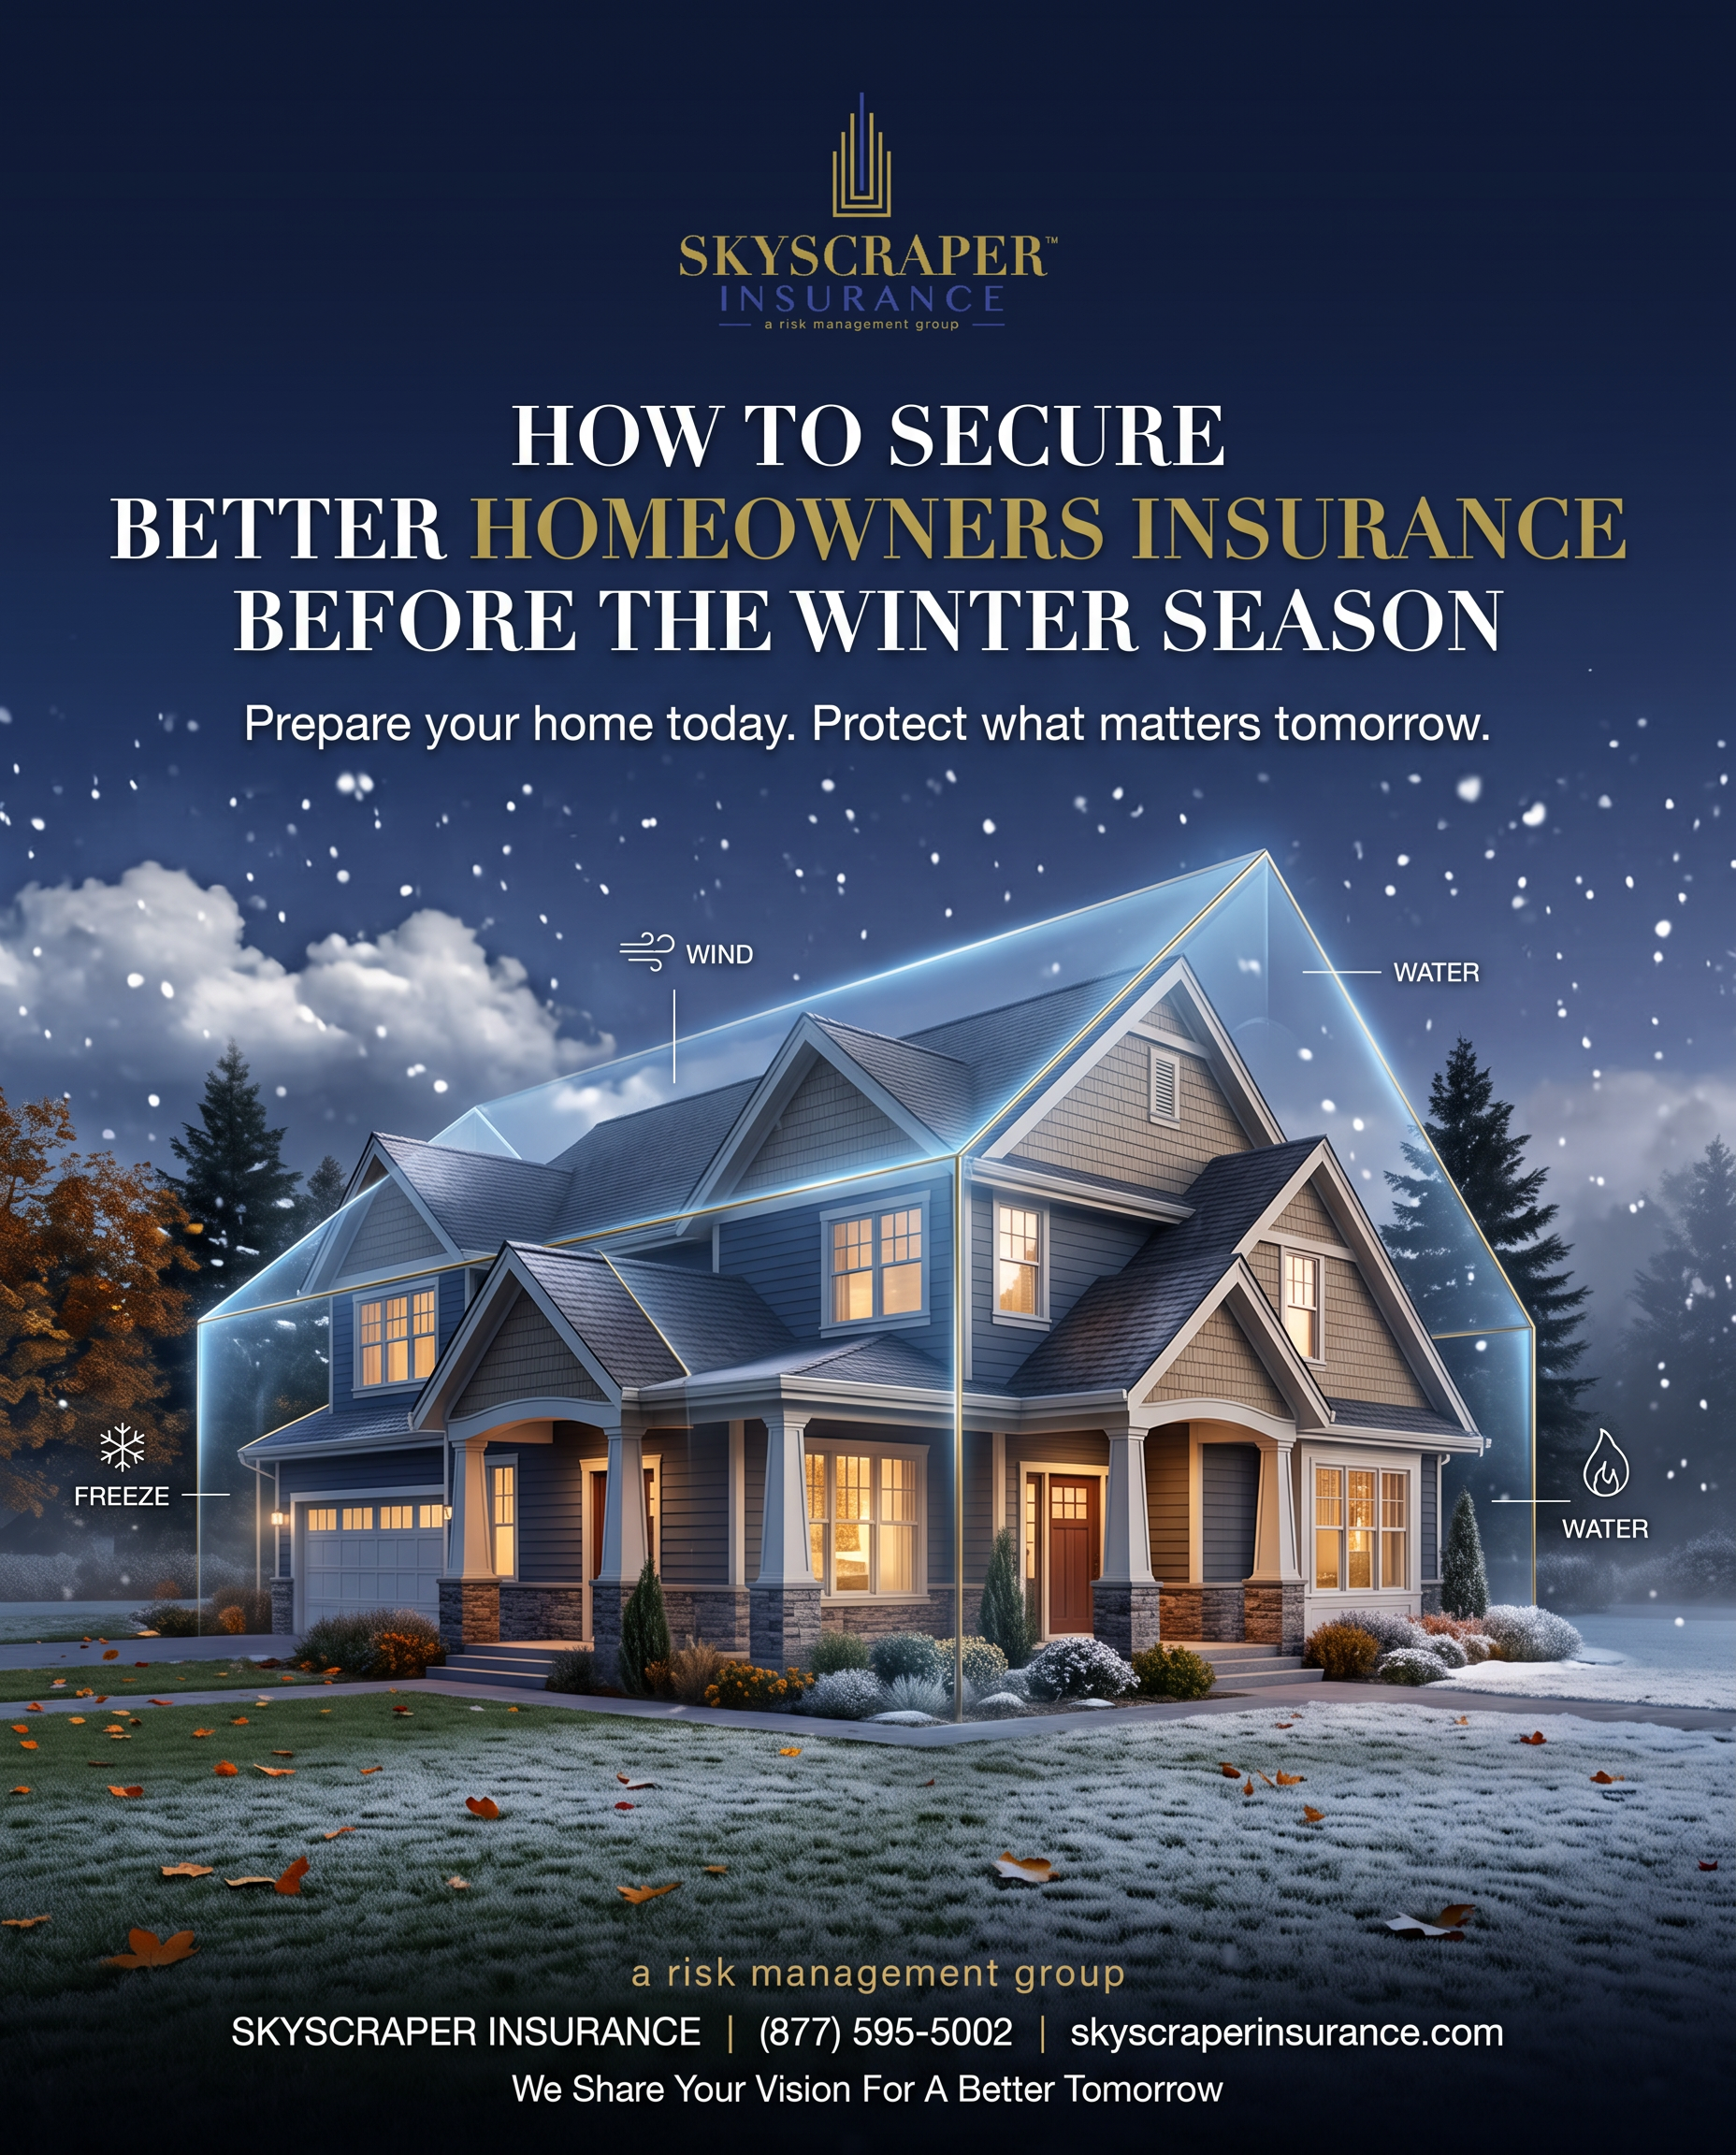
- Wind, Falling Limbs, and Roof Integrity: Autumn low-pressure systems bring gusting winds that bring down dead tree branches onto roof decking, gutters, and siding. If pre-existing roof wear or deferred maintenance is detected, claims adjusters often scrutinize payouts.
- Rapid Freeze Cycles and Pipe Vulnerabilities: As late autumn approaches, sudden overnight temperature drops cause uninsulated supply pipes, outdoor spigots, and crawlspace plumbing to burst, unleashing tens of thousands of dollars in water damage within hours.
- Heating Fire Hazards: October marks the reactivation of furnaces, space heaters, and wood-burning fireplaces. Heating equipment failure and creosote buildup remain the second-leading cause of home fires nationwide.
- Surface Water Runoff & Sump Pump Failure: Autumn deluges can saturate soil and overwhelm perimeter drainage systems, leading to basement flooding that standard property policies do not cover.
The Replacement Cost Deficit:
Over the past few years, residential construction, roofing, and skilled trade labor costs have steadily increased. If your dwelling limit was set years ago without adjusting for inflation, a total or major partial loss could leave you tens of thousands of dollars short of the funds required to rebuild to your original specifications.
2. Four Critical Safeguards for Your Personal Home Architecture
To ensure your homeowners policy performs when seasonal perils strike, audit your binder for these essential coverage pillars:
Extended or Guaranteed Replacement Cost
Ensure your policy includes an Extended Replacement Cost endorsement (providing an additional 25% to 50% above your base dwelling limit) or a Guaranteed Replacement Cost endorsement. This provision provides a dedicated financial cushion to absorb unexpected regional spikes in building material prices and contractor fees following a localized storm or fire.
Water Backup and Sump Overflow Endorsement
A standard homeowners policy explicitly excludes damage caused by water that backs up through sewers, drains, or overflows from a sump pump basin. Adding a dedicated Water Backup of Sewers and Drains endorsement ensures that finished basements, mechanical rooms, custom flooring, and lower-level living spaces are fully protected from costly indoor inundation.
Scheduled Personal Property for Family Valuables
Basic personal property coverage places strict sub-limits, often as low as $1,500 to $2,500. on specialized categories such as fine jewelry, luxury watches, fine art, rare musical instruments, and family silver. Scheduling these treasures individually ensures agreed-value reimbursement with zero out-of-pocket deductibles in the event of theft, loss, or storm damage.
Comprehensive Personal Umbrella Liability
The holiday season brings higher visitor traffic to your home. If a guest, delivery courier, or family visitor slips on wet exterior leaves, icy steps, or a loose porch board, medical costs and legal claims can quickly eclipse standard $300,000 baseline liability limits. An integrated Personal Umbrella Policy ($1M to $5M+) extends worldwide excess liability to shield your family’s investment accounts, savings, and future earnings.
Standard Homeowners Coverage vs. The Skyscraper Standard
Review how a tailored personal insurance architecture protects your family home compared to a generic retail policy:
| Coverage Area | Basic Homeowners Policy Reality | The Skyscraper Personal Architecture | The Homeowner Advantage |
| Dwelling Rebuild | Strict cap at stated policy limit; vulnerable to construction surge inflation. | Extended Replacement Cost (125%–150%): Generous buffer above stated limit. | Guarantees complete restoration to original craftsmanship without out-of-pocket gaps. |
| Drain & Sump Water | Excluded under standard policy forms; total out-of-pocket remediation cost. | Water Backup & Sump Overflow Endorsement: Broad limits up to $50,000+. | Restores finished basements, drywall, heating equipment, and personal belongings. |
| High-Value Assets | Blanket contents coverage subject to rigid category dollar caps. | Itemized Scheduled Floater: Agreed-value valuation without deductible friction. | Full replacement value for heirlooms, jewelry, and fine art without standard caps. |
| Guest Slip & Fall | Base personal liability capped at $300,000, risking personal assets in a lawsuit. | Integrated Personal Umbrella Tower: Seamless $1M to $5M+ excess protection. | Comprehensive legal defense and asset immunity against premises liability claims. |
Take Control: Learn More
October is the ideal moment to take proactive control of your personal risk management. The comfort and warmth of your home depend on the strength of the financial protections surrounding it. Waiting for a winter freeze, chimney fire, or autumn windstorm to test your policy leaves your household exposed to unexpected out-of-pocket losses.
At Skyscraper Insurance, our personal lines risk advisors bring executive-level diligence to your personal home insurance. We perform comprehensive policy audits, verify dwelling replacement valuations, eliminate hidden exclusions, and partner with top-tier personal lines insurers to deliver seamless, high-net-worth protection for your family home.
Is your home protected by coverage engineered for the seasons ahead, or will upcoming weather reveal costly policy exclusions?
Start the month with complete confidence in your home’s security. Connect with our personal insurance advisory team today and Learn More. We will conduct a thorough, complimentary policy review to ensure your home and family remain completely protected under every sky. Visit us at Skyscraper Insurance to schedule your personal home coverage review today.