Shielding Your Personal Balance Sheet and Future Earnings from Catastrophic Liability
In the discipline of wealth management, families and business owners invest immense discipline into building financial independence. You optimize investment portfolios, maximize tax efficiency, structure trusts, and acquire high-value personal assets.
Yet, when evaluating asset protection, many individuals operate under a precarious assumption: that standard auto and homeowners insurance limits provide an unassailable financial fortress.
The modern legal environment is defined by social inflation, aggressive plaintiff litigation, and historically high personal injury judgments.
At Skyscraper Insurance, we treat personal risk with the same technical rigor applied to institutional balance sheets. True wealth preservation requires an integrated, high-capacity Personal Umbrella Insurance architecture engineered to absorb catastrophic legal shocks and preserve your family’s legacy.
1. The Anatomy of Modern Personal Liability Exposures
Standard personal insurance policies are designed to handle routine, localized property losses. However, the legal landscape of catastrophic injury claims has shifted dramatically:
- Severe Automotive Liabilities: Modern vehicle values, runaway medical care inflation, and extended lost-wage claims routinely push serious highway accident liabilities past $1,000,000. If an accident results in long-term disability or wrongful death, standard $250,000 or $500,000 auto liability limits disappear almost instantly.
- Premises and Social Hosting Exposures: Entertaining guests, hosting family gatherings, or owning seasonal vacation properties introduces substantial premises liability. Serious slip-and-fall incidents, swimming pool drownings, balcony failures, or dog-related injuries can trigger devastating personal lawsuits alleging homeowner negligence.
- Youthful and Inexperienced Drivers: Households with teenage or young adult drivers carry statistically higher accident risks. Under legal doctrines of parental liability, parents are frequently held financially responsible for catastrophic damages caused behind the wheel by their dependents.
- Reputational, Defamation, and Digital Claims: Modern liability extends beyond physical harm. Allegations of online defamation, libel, slander, invasion of privacy, or cyberbullying involving household members can trigger expensive litigation that standard homeowners policies explicitly exclude.
The Asset Exposure Reality:
When an adverse legal judgment exceeds your underlying policy limits, courts do not forgive the remaining balance. Savings accounts, taxable brokerage portfolios, equity in secondary properties, and future wages can be garnished to satisfy court-ordered judgments.
2. Technical Pillars of a Comprehensive Personal Umbrella Tower
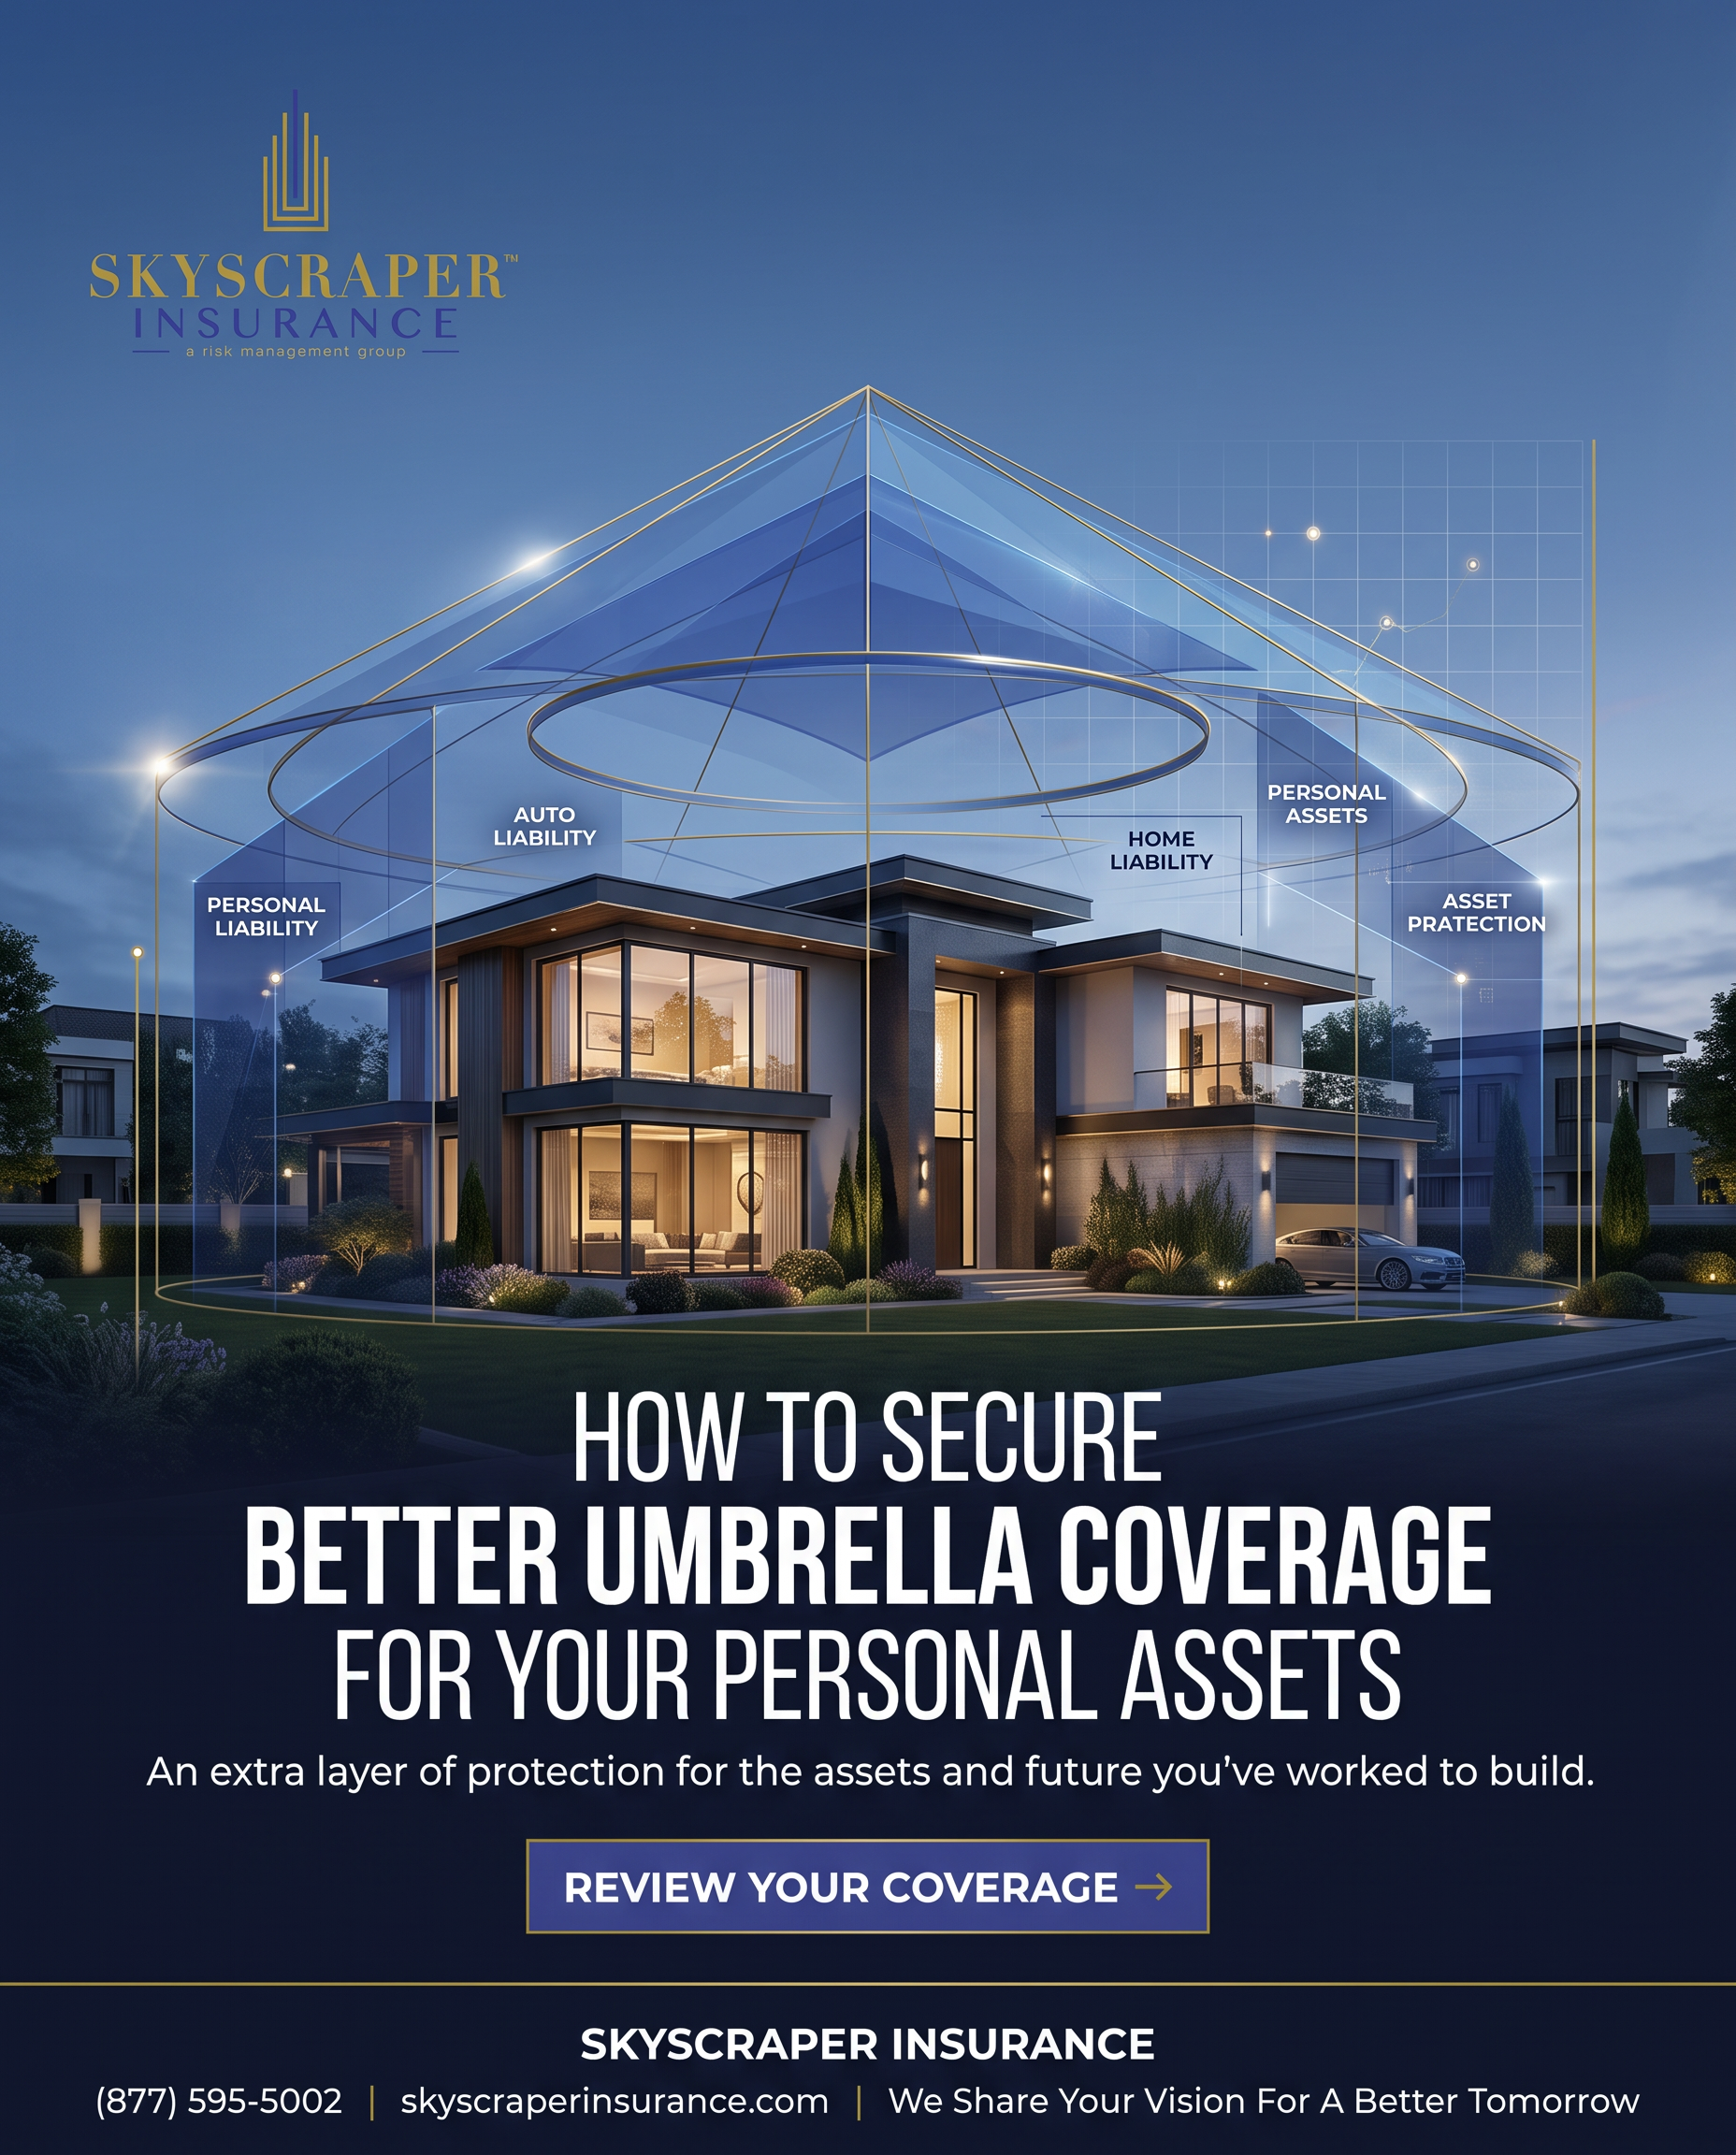
A Personal Umbrella Policy is not a luxury add-on; it is the ultimate backstop of your family’s financial security. It acts as an overarching shield, sitting directly atop your underlying auto, homeowners, watercraft, and secondary property binders:
Substantial Excess Liability Limits ($1M to $10M+)
Umbrella policies provide pure excess liability coverage in increments of $1,000,000. Once your primary auto or homeowners limits are paid out, the umbrella drops down to cover remaining legal judgments and settlements, protecting your personal estate from liquidation.
Full Coverage for Specialized Legal Defense Costs
Mounting a sophisticated legal defense against complex bodily injury claims requires high-caliber trial attorneys, accident reconstruction experts, and specialized forensic accountants. A properly structured umbrella policy funds your complete legal defense outside and in addition to policy limits, meaning defense bills do not erode the capital available to pay a settlement.
Expanded Underlying Coverage Drop-Down
A robust personal umbrella policy often provides broader protection than underlying forms. In instances where an auto or homeowners policy contains narrow terms, such as certain international travel liabilities, false arrest claims, or slander allegations, the umbrella can drop down to serve as primary coverage, subject to a nominal self-insured retention (deductible).
Harmonized Underlying Attachment Points
An umbrella policy is only as sound as the foundation beneath it. If your umbrella requires an underlying auto limit of $500,000, but your active auto policy was inadvertently set at $250,000, a $250,000 coverage gap opens. In a major claim, you are personally liable for that middle layer before the umbrella attaches. Auditing and aligning underlying attachment points across all vehicles, properties, and recreational toys ensures seamless continuity.
Standard Primary Policies vs. The Skyscraper Umbrella Shield
Review how an engineered personal umbrella program protects your family’s financial future compared to baseline policies:
| Liability Dimension | Baseline Auto & Homeowners Coverage | The Skyscraper Umbrella Architecture | Household Asset Advantage |
| Liability Ceilings | Capped at | Excess Towers ( | Completely insulates investment accounts, home equity, and trusts. |
| Legal Defense Fees | Often erodes policy limits or capped by carrier litigation panels. | Defense Outside Limits: Carrier funds top-tier independent legal counsel. | Preserves full policy capital exclusively for settlement or judgment resolution. |
| Personal Injury Claims | Excludes non-physical torts like libel, slander, and invasion of privacy. | Broadened Personal Injury Endorsement: Full affirmative defense. | Protects against social media defamation, false arrest, and privacy claims. |
| Worldwide Protection | Strictly territorial; restricted to domestic jurisdictions. | Global Excess Territorial Reach: Coverage follows your family worldwide. | Extends liability protection during foreign vacations and international travel. |
Take Control: Learn More
Building wealth requires decades of focus, discipline, and calculated risk; protecting that wealth from an unexpected legal judgment requires a single afternoon of structured diligence. Leaving your personal balance sheet exposed to the realities of modern litigation with baseline insurance limits is an unhedged risk your family cannot afford to take.
At Skyscraper Insurance, we specialize in high-net-worth personal risk engineering and wealth preservation. Our advisors conduct comprehensive personal liability audits, evaluate household exposure profiles, align underlying attachment points, and structure cost-effective, high-capacity umbrella towers with premier global personal lines underwriters.
Are your personal savings, property equity, and future earnings fortified by an overarching liability shield, or could a single lawsuit compromise your family’s financial security?
Take command of your asset protection strategy today. Connect with our personal lines advisory team and Learn More. We will perform a complete, confidential audit of your active personal coverage to eliminate liability gaps and ensure your life’s work remains fully protected under every sky.
Visit us at Skyscraper Insurance to schedule your personal umbrella review today.