Honoring the Discipline of Service: Why an Umbrella Policy Matters for Added Financial Protection this Veterans Day
Veterans Day serves as an enduring reminder of what it takes to protect what matters most: strategic foresight, relentless discipline, and building defenses that hold firm under extraordinary pressure. In military doctrine, an operation is never planned around the best-case scenario.
In civilian life, veterans, active service members, and accomplished professionals bring that same steady discipline to building financial independence. You build businesses, grow investment portfolios, manage family real estate, and establish legacies meant to endure for generations.
A catastrophic highway collision, a serious injury on your property, or an accident involving a young family driver can deplete standard primary limits in the opening hours of a lawsuit.
Once that primary limit is exhausted, your frontline insurer steps aside. Without an overarching defense in place, personal assets are immediately exposed.
At Skyscraper Insurance, we believe true asset defense requires strategic depth. This Veterans Day, honor the principle of preparedness by reinforcing your financial fortress with an engineered Personal Umbrella Insurance tower.
1. The Battlefield of Modern Liability: Why Frontline Limits Fall
- High-Severity Automotive Collisions: Runaway medical inflation, lifetime rehabilitation costs, and lost-wage claims for high-earning third parties quickly run into the millions. A $500,000 auto bodily injury limit covers only a fraction of a multi-vehicle highway judgment.
- Premises and Social Host Exposures: Balcony collapses, pool mishaps, or dog-related injuries can generate multi-million-dollar claims under premises liability doctrine.
- Youthful Driver Liabilities: Young drivers carry statistically higher accident risks.
- The Erosion of Legal Defense: Complex bodily injury litigation requires accident reconstruction experts, medical authorities, and seasoned trial attorneys.
The Asset Exposure Reality:
Just as an unfortified position invites strategic compromise, an underinsured liability loss invites court-ordered asset enforcement. Judgments exceeding primary policy limits place non-retirement investment portfolios, secondary property equity, savings, and future wages squarely within reach of civil creditors.
2. Strategic Defense Architecture: How Personal Umbrella Coverage Operates
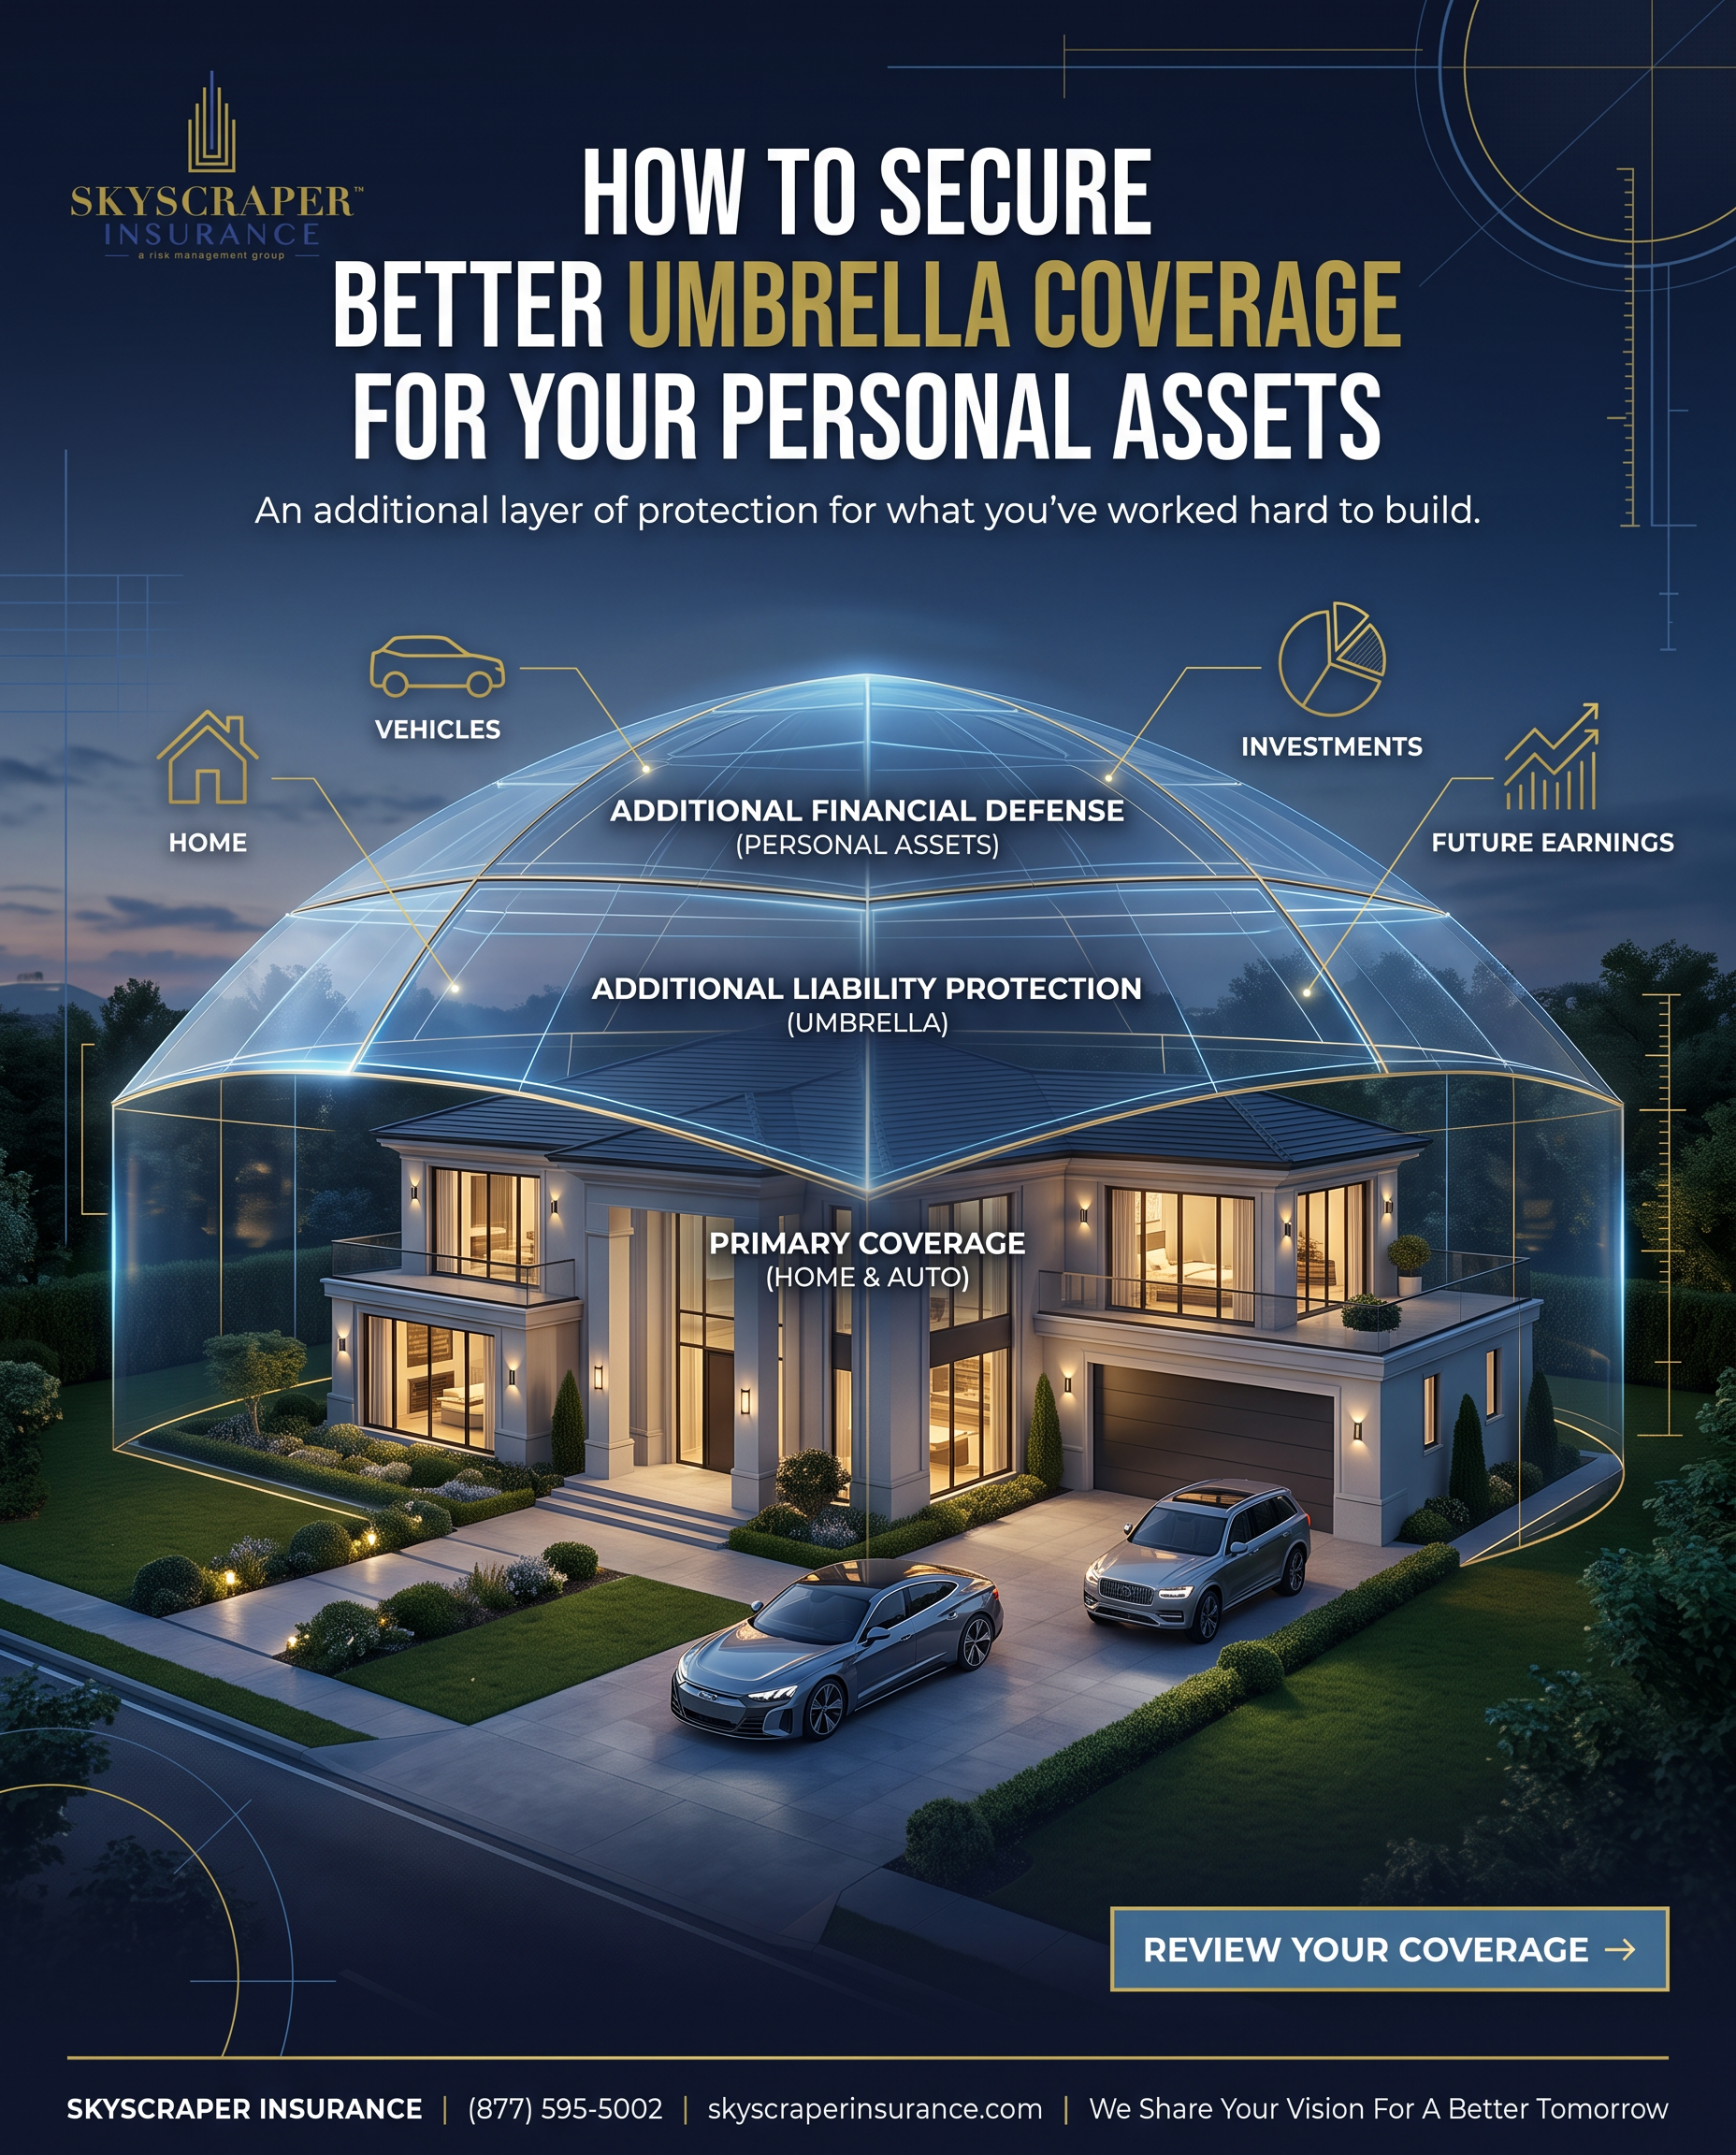
A Personal Umbrella Policy (PUP) is an engineered excess liability reserve that sits directly above primary auto, homeowners, and watercraft policies:
High-Capacity Excess Reserves ($1M to $5M+)
Umbrella policies provide pure excess coverage in increments of $1,000,000.
Legal Defense Outside Policy Limits
Defending your name and assets against aggressive plaintiff litigation demands premier legal representation.
Broadened Defensive Perimeter
An umbrella policy often covers operational gaps excluded by standard underlying homeowners forms.
Seamless Attachment Point Alignment
In military logistics, an uncoordinated perimeter creates an exploitable gap. An umbrella policy requires specific baseline limits on underlying policies (typically 500k auto and $300k to $500k home). Auditing attachment points ensures an unbroken defense line across all family vehicles, properties, and recreational assets.
Standard Primary Policy vs. The Skyscraper Defensive Standard
| Strategic Exposure | Standard “Max Limit” Policy ($500k) | The Skyscraper Umbrella Tower ( | Balance Sheet Resilience |
| Severe Highway Collision | Carrier pays | Seamless Excess Drop-Down: Umbrella absorbs the remaining $1.5M+ balance. | Shields liquid capital, brokerage accounts, and future income from seizure. |
| Legal Defense Costs | Defense fees erode policy limits or cease once the cap is paid. | Defense Outside Limits: Insurer funds premier trial counsel until final resolution. | Preserves 100% of policy limits exclusively for settlement or judgment resolution. |
| Personal Injury & Defamation | Explicitly excludes non-physical torts like libel, slander, or digital claims. | Affirmative Personal Injury Endorsement: Comprehensive defense against non-physical claims. | Protects household members against modern digital and social media litigation. |
| Territorial Scope | Strictly limited to domestic jurisdictions and Canada. | Worldwide Liability Reach: Coverage follows you globally on duty or leisure. | Insulates personal assets during international travel and vehicle rentals abroad. |
Take Control: Price an Extra $1-$5M in Limits
Securing an additional $1,000,000 to $5,000,000 in excess liability protection typically costs just a fraction of your primary insurance premiums.
At Skyscraper Insurance, we specialize in personal risk engineering and wealth preservation for families, business owners, and veterans. Our advisors audit your underlying policies, close attachment gaps, and construct tailored excess liability towers with premier global underwriters.
Fortify your position today. Connect with our personal lines advisory team and Price an extra 5M in limits. We will perform a complete, confidential audit of your active liability policies and structure an umbrella program engineered to protect your balance sheet, your family, and your legacy.
Visit us at Skyscraper Insurance to review your coverage and secure your excess liability protection today.